Stochastic Modelling金融Paper范文|Markov Chain、HMM与金融预测
Stochastic Modelling(随机建模)是Quantitative Finance、Financial Management、Actuarial Science和Investment Analysis课程中经常出现的主题。
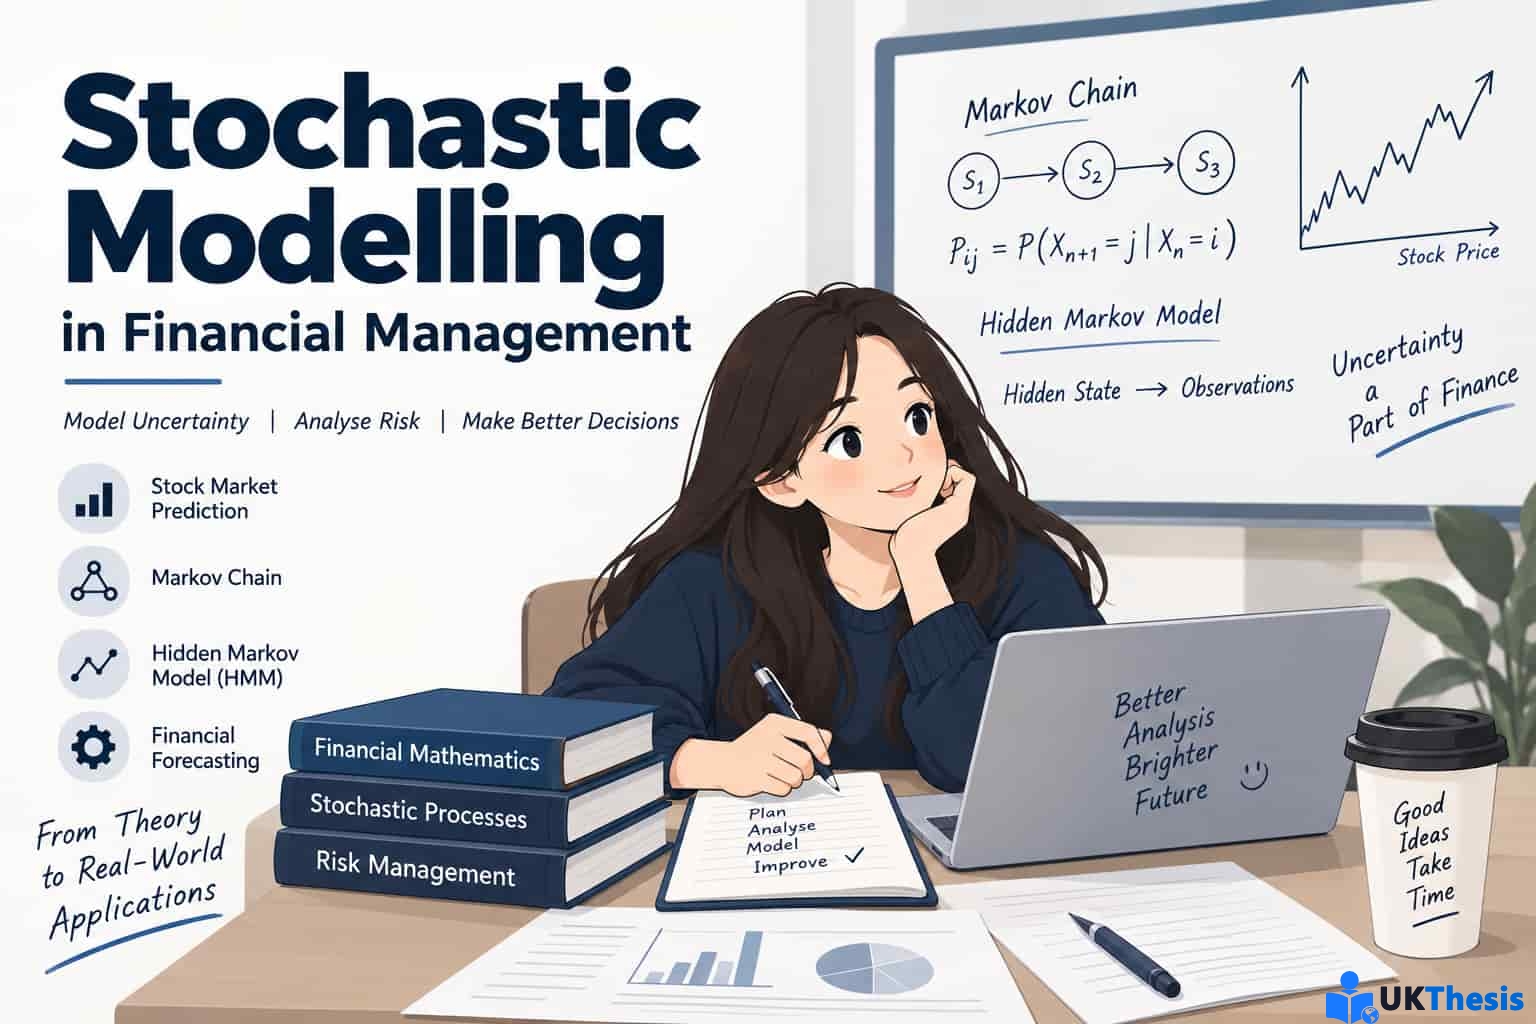
它真正解决的问题并不是“准确预测未来”,而是承认未来存在不确定性,然后用概率、状态转移和统计模型去描述不同结果发生的可能性。
这一点特别重要。金融市场每天都在变化,股票价格、利率、波动率和经济因素都不是固定值。如果用完全确定性的模型去解释这些问题,往往会把现实想得过于简单。
范文类型:Finance Paper / Quantitative Finance
核心主题:Stochastic Modelling / Financial Forecasting
主要模型:Markov Chain、Hidden Markov Model、APT
应用方向:Stock Market、Asset Pricing、Risk Management
Aim:为什么金融里需要Stochastic Modelling?
In finance, future outcomes are uncertain. Investors, firms and financial institutions must make decisions without knowing exactly how prices, interest rates or market conditions will change.
Stochastic models are designed to incorporate this uncertainty.
Unlike deterministic models, which assume that a given set of inputs will always produce one specific outcome, stochastic models allow multiple possible outcomes with different probabilities.
这就是为什么随机模型在Finance里特别常见。它不是告诉你“明天股价一定是多少”,而是告诉你:在某些假设下,不同结果出现的概率大概是多少。
Why Stock Markets Are Difficult to Predict
Individuals and companies continuously face financial decisions about spending, saving and investing.
Stock markets are particularly difficult because prices respond to many factors, including company information, macroeconomic conditions, interest rates, investor expectations and unexpected events.
There is no single model that can predict daily stock-price movements with complete accuracy.
For this reason, financial researchers use a variety of stochastic approaches, including random walks, Markov chains, Hidden Markov Models and diffusion-based models.
| Model | Basic idea |
|---|---|
| Random Walk | Future price changes are difficult to predict from past movements alone. |
| Markov Chain | Future state depends primarily on the current state. |
| Hidden Markov Model | Observed market behaviour is influenced by an unobservable hidden state. |
| Brownian Motion | Continuous random movement used in many financial pricing models. |
Markov Chain
A Markov Chain is a stochastic process in which the probability of the next state depends on the current state rather than the full historical path.
Suppose a market is classified into several possible states, such as:
Increase → Stable → Decrease
A transition matrix can then be used to describe the probability of moving from one state to another.
For example, if the market is currently in an “Increase” state, the model may estimate different probabilities that the next period will remain “Increase”, move to “Stable”, or move to “Decrease”.
简单理解:
Markov Chain最重要的假设不是“历史完全没用”,而是当前状态已经包含了预测下一状态所需的主要信息。
This property makes Markov models useful when financial conditions can be represented by discrete states.
Markov Chain在股票预测中的局限
Markov Chain can be useful for short-horizon state prediction, but its reliability may decline when predictions extend further into the future.
The reason is simple: each additional step introduces further uncertainty.
If a model predicts tomorrow's market state and then uses that predicted state to estimate the following day, prediction errors can accumulate.
所以一篇好的Finance Paper不能只写“Markov Chain is powerful”。更合理的写法应该是:
Markov Chain在短期状态分析中可能有用,但其长期预测能力受到状态定义、历史数据和转移概率稳定性的限制。
Hidden Markov Model(HMM)
A Hidden Markov Model extends the Markov idea by assuming that the true underlying state cannot be directly observed.
Instead, researchers observe signals that are generated by that hidden state.
In financial markets, the hidden state might represent conditions such as:
high-volatility regime;
low-volatility regime;
bullish market regime;
bearish market regime.
Investors do not directly observe the “true regime”. They observe returns, volatility and other market variables, and the HMM estimates which hidden state is most likely.
这比普通Markov Chain多了一层:我们看到的是市场表现,但真正的市场状态可能隐藏在背后。
Deterministic vs Stochastic Modelling
| Model Type | Main assumption |
|---|---|
| Deterministic | Same inputs lead to one predictable output. |
| Stochastic | Inputs and outcomes may contain randomness and probability. |
Deterministic models are useful when assumptions are relatively stable and predictable.
However, financial markets contain uncertainty, which is why stochastic modelling is often more appropriate for risk analysis, asset pricing and scenario simulation.
这并不意味着stochastic一定“更高级”。模型是否合适,关键要看research Question。
Modelling the Future:Forecast不是Prediction Guarantee
Financial forecasting uses historical and current information to estimate future possibilities.
The word “forecast” is important because financial models normally produce conditional expectations rather than guarantees.
Even a statistically strong model can fail when:
market structure changes;
unexpected news occurs;
historical relationships break down;
investor behaviour changes;
model assumptions are incorrect.
所以Finance里真正专业的表达通常不是:
“The model predicts the stock price.”
而是:
“The model estimates the probability or expected distribution of future outcomes under specified assumptions.”
Arbitrage Pricing Theory(APT)
Arbitrage Pricing Theory extends asset-pricing analysis beyond a single market factor.
Unlike CAPM, which focuses mainly on the relationship between an asset and the market portfolio, APT assumes that returns may be influenced by multiple systematic factors.
These factors may include:
• inflation;
• interest rates;
• production growth;
• term structure;
• broader macroeconomic changes.
In practice, APT can be estimated using techniques such as regression analysis and factor analysis.
APT和前面的Markov Model并不是同一种模型,但它们都体现了一个共同思路:金融结果不是由一个完全确定的因素决定,而是受到多个不确定因素共同影响。
Stochastic Techniques in Financial Management
Stochastic techniques can be applied in several areas of financial management.
| Application | Purpose |
|---|---|
| Stock Market Analysis | Estimate probabilities of different price or market states |
| Risk Management | Model possible losses under uncertainty |
| Asset Pricing | Estimate expected returns under uncertain factors |
| Portfolio Management | Evaluate return and risk distributions |
| Scenario Analysis | Examine alternative future outcomes |
Advantages and Limitations
Stochastic models are useful because they allow uncertainty to be incorporated directly into financial analysis.
They are particularly valuable when future outcomes cannot be represented by one fixed forecast.
However, these models also have limitations.
They depend heavily on:
the quality of historical data;
the assumptions used to define states or distributions;
parameter stability;
computational complexity;
whether past market relationships remain relevant.
A sophisticated model can therefore still produce misleading results if its assumptions do not match market reality.
Critical Analysis:模型越复杂就越好吗?
Not necessarily.
Complex stochastic models can capture more sources of uncertainty, but complexity can also make models harder to interpret and validate.
For smaller or medium-sized problems, relatively simple models may be easier to test and explain.
Large-scale stochastic programmes can require specialised optimisation methods and significantly greater computing resources.
所以选模型时不能只看“高级感”,而应该看:
模型是否真的回答Research Question、数据是否支持、假设是否合理,以及结果能不能解释。
Financial Decision-Making and Uncertainty
Financial markets exist partly to facilitate decisions across time: spending today, saving for the future, borrowing, investing and transferring risk.
Because these decisions depend on uncertain future outcomes, stochastic modelling provides a natural framework for thinking about financial risk.
However, quantitative models should not be treated as substitutes for judgement.
Financial decisions are also influenced by market structure, regulation, behavioural factors and unexpected events that may not be fully captured by historical models.
Conclusion
Stochastic modelling provides an important framework for analysing uncertainty in finance.
Markov Chains can represent transitions between financial states, while Hidden Markov Models allow analysts to estimate unobservable market regimes from observable data.
APT demonstrates how multiple systematic factors may influence asset returns, while stochastic techniques more generally support risk management, portfolio analysis and financial forecasting.
However, no model can remove uncertainty completely.
The real value of stochastic modelling is not that it predicts markets perfectly, but that it provides a structured way to understand probabilities, risk and alternative future outcomes.
对于Finance Paper来说,这就是比较成熟的结论:模型不是水晶球,它更像一张概率地图。
FAQ
Q:这篇属于Finance还是Methodology?
A:主体属于Finance Paper / Quantitative Finance。虽然介绍了研究方法和模型,但它不是单独的Research Methodology章节。
Q:Markov Chain可以准确预测股票吗?
A:不能保证准确。它更适合估计状态之间的转移概率,尤其在短期状态分析中可能有参考价值。
Q:Hidden Markov Model和Markov Chain有什么不同?
A:Markov Chain通常直接观察状态,而HMM假设真正状态不可直接观察,只能通过价格、波动率等数据间接估计。
Q:金融Paper一定要有公式吗?
A:不一定。是否需要公式取决于课程和题目要求。理论型Paper可以重点解释模型机制和局限,Quantitative assignment则通常需要计算或数据分析。
相关阅读
如果想继续了解Finance Paper整体结构,可以阅读站内金融论文与Finance Assignment写作指南。
如果研究方向偏Asset Pricing,可以继续阅读CAPM、APT、Portfolio Theory和Risk Management相关范文。
如果已经有Quantitative Finance题目、模型或初稿,也可以通过研究问题梳理、模型选择、结果解释、Critical Analysis和英文表达修改等方式完善已有内容。
```